Saldo Tabungan Emas BRI Group Capai 20 Ton hingga September 2026
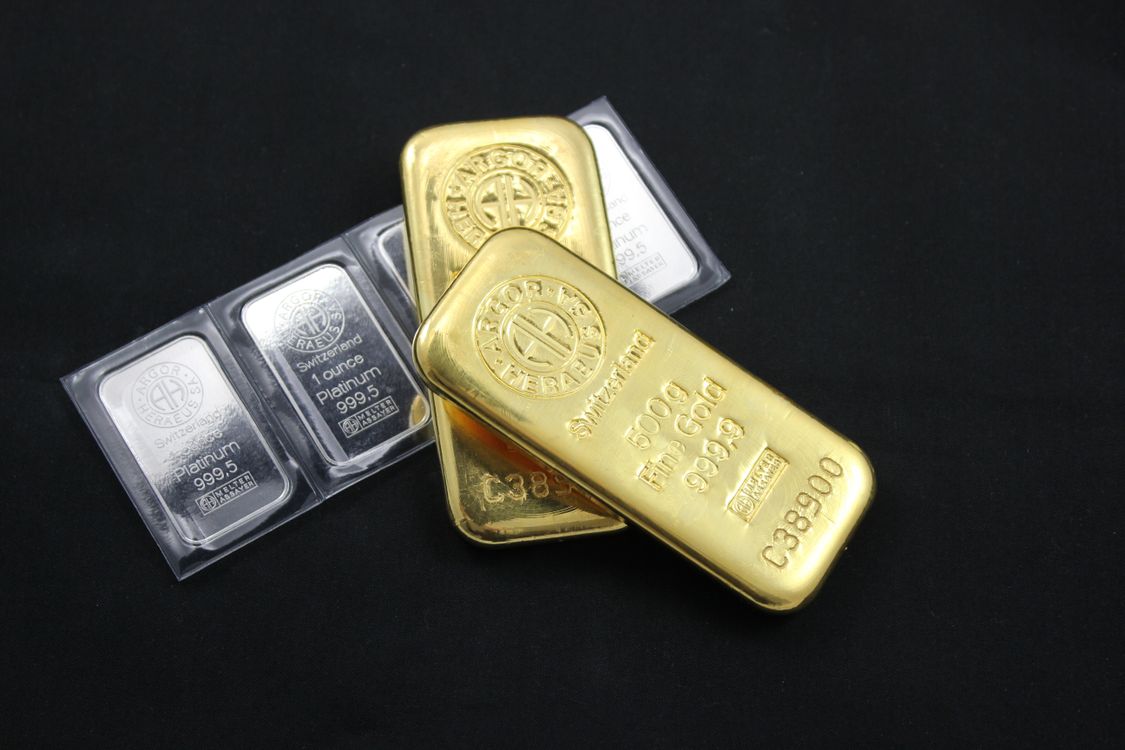
Pencapaian saldo tabungan emas 20 ton hingga September 2026 menandai pergeseran penting dalam strategi BRI Group.previously focused on expanding the customer base and credit distribution, the Group now has a more diversified instrument for meeting the liquidity needs of micro businesses and households while capturing value from the gold market. Alongside the 20-ton balance, trading volume reached 13.2 tons. These two figures show a business that is no longer merely a complementary product, but has the potential to become a new growth engine. However, the strategic meaning of the achievement cannot be assessed solely from the number of tons. The main question is whether gold can generate recurring, high-quality revenue while also expanding the financial inclusion of the 33.8 million micro borrowers within the BRI Group ecosystem.
Dari produk pelengkap menjadi mesin pertumbuhan baru
Gold savings provide BRI Group with an alternative source of income outside conventional credit interest. Through the branch network of Pegadaian and the broader BRI Group customer base, the business can generate revenue from transaction spreads, service fees, and distribution activities. This is particularly relevant when the cost of funds is relatively high or credit growth is under pressure. A more active gold ecosystem creates opportunities for customers to purchase, sell, and use gold as part of their financial planning. For the Group, the strategic value lies in increasing the frequency and quality of customer transactions rather than simply adding more accounts. A customer who buys gold regularly, understands its risks, and uses related services will create greater economic value than a customer who makes only one purchase for promotional purposes.
The integration of gold savings and Pegadaian’s pawning operations also creates a two-way customer journey. Customers who need liquidity can bring gold as collateral, while those seeking asset protection can purchase gold through savings products. The transaction does not have to end at the point of sale. It can continue through pawning, gold trading, and other financial services tailored to micro and small businesses. This creates an asset formation pipeline, or a flow in which customers gradually build financial assets and subsequently access financing based on those assets. The pipeline is not automatic, however. Its effectiveness depends on customer trust, transparent pricing, simple processes, and products that genuinely match customers’ cash-flow capacity.
33,8 juta debitur mikro: opportunity that requires careful conversion
The 33.8 million micro borrowers represent a large potential market, but they should not be treated as a captive pool of gold customers. A debtor generally has different priorities from an investor: business continuity, working capital, and debt repayment come before asset accumulation. The opportunity lies in offering a structured path toward asset formation, especially for business owners whose daily cash reserves are vulnerable to shocks or unexpected expenses. Gold can serve as a more flexible liquid reserve, while productive-asset financing can help the same customer acquire equipment, inventory, or other assets that increase business capacity. The key is to connect these two needs without encouraging customers to borrow excessively merely to purchase gold.
Conversion from debtor to gold saver should therefore be based on suitability rather than aggressive cross-selling. Customers with unstable income, high debt servicing pressure, or limited financial knowledge may need emergency reserves and debt restructuring before they can consider long-term asset accumulation. BRI, PNM, and Pegadaian can use their respective strengths in this process: BRI in credit and business services, PNM in serving the ultra-micro segment, and Pegadaian in physical gold and collateral-based transactions. This division of roles allows the Group to create a more complete customer journey. At the same time, product boundaries and credit assessments must remain independent so that gold ownership does not become a substitute for proper business analysis.
Synergy of the ultra-micro holding: more than customer cross-selling
Synergy within the ultra-micro holding should be measured by more than the number of customers transferred between business units. A meaningful synergy improves customer understanding, reduces duplicated costs, accelerates service delivery, and expands the range of relevant financial solutions. A unified customer view can help identify business owners who require working capital, those with surplus cash who may be interested in gold savings, and those seeking short-term liquidity through pawning. The same data infrastructure can also support more targeted financial education, such as explaining how gold prices fluctuate, how pawning costs work, and when emergency reserves should be prioritized over investment products.
Beyond that, the integration must address operational and risk management. Gold trading involves price volatility, inventory exposure, and differences between buying and selling prices. Meanwhile, credit expansion is tied to repayment capacity and sector-specific risks. Combining these activities without clear controls could create conflicts of interest, including the temptation to offer high-cost credit merely to generate transaction volume. The healthier approach is to establish a single customer-quality framework while maintaining distinct risk standards for each product. In this structure, the 33.8 million micro borrowers become a long-term relationship base rather than a short-term sales target.
Reading the 13.2-ton trading volume
The 13.2-ton trading volume provides a second lens for evaluating the gold business. If compared directly with the 20-ton balance, the volume equals approximately 66% in arithmetic terms. That comparison should not be interpreted as a formal turnover ratio, because a balance is a stock measured at a particular point in time, whereas trading volume is a flow accumulated over a period. Nevertheless, the figure indicates that the business is not completely dependent on new deposits of gold. Active transactions among existing customers also contribute to revenue generation and customer engagement. For a savings platform, this is an important sign of product utility.
High trading activity also requires careful interpretation. Volume can increase because of stronger customer demand, but it can also reflect wider price differences, more frequent transactions, or changes in the composition of products sold. Revenue quality therefore depends on the net spread after inventory movements, operational costs, and risk provisions. It also depends on whether trading activity produces repeat transactions or merely one-off purchases. The most valuable growth occurs when customers understand the difference between gold as a liquid asset, gold as collateral, and gold as a long-term investment. Clear disclosure and consistent execution are essential for converting trading enthusiasm into sustainable trust.
Strategies for turning quantity into revenue quality
To make gold a durable growth engine, BRI Group should focus on several mutually reinforcing indicators:
- Customer activity: the proportion of gold customers making repeat transactions, not only the total number of new accounts.
- Revenue resilience: the contribution of net spreads and service fees relative to credit income, adjusted for operating costs and inventory risk.
- Financial inclusion: the number of micro customers who gain access to secure savings, appropriate financing, or emergency liquidity through the integrated ecosystem.
- Operational efficiency: the cost of processing purchases, sales, pawning, and verification across channels.
- Customer outcomes: improvements in liquidity, financial resilience, and productive-asset ownership among micro business owners.
Digitalization can support these indicators by providing transparent buying and selling prices, real-time balance information, transaction histories, and straightforward instructions for every product. Gold ownership can be made more accessible through small recurring purchases, while Pegadaian’s physical network can provide verification and liquidation channels for customers who need face-to-face services. Financial education should also be embedded in the process, particularly for customers entering the gold market for the first time. Education is not a separate promotional activity; it is part of product design because it directly affects whether customers use the instrument appropriately.
Determining whether the 20-ton achievement changes the business
The 20-ton gold savings balance is strategically meaningful, but it does not by itself prove that BRI Group has created a new high-quality revenue stream. Its long-term significance will be determined by three conditions: recurring customer transactions, disciplined management of price and inventory risks, and measurable improvements in the financial resilience of micro customers. The 13.2-ton trading volume suggests that customer activity is already becoming important, while the 33.8-million-debtor universe provides ample room for an inclusive asset-formation model. The challenge is to turn that scale into relevance rather than merely volume.
The most convincing evidence of success will emerge when gold savings, productive-asset financing, and collateral-based transactions reinforce one another without weakening underwriting discipline. In that scenario, gold becomes more than a product that adds tons to the balance sheet. It becomes a bridge between emergency liquidity, long-term asset formation, and sustainable business growth. The achievement of 20 tons therefore marks the beginning of a more rigorous phase: measuring income quality, customer benefit, and operational discipline alongside asset growth. Only with that balance can the gold ecosystem become a genuine engine of BRI Group’s future performance.
Disclaimer
Artikel ini bersifat edukasi dan informasi umum, bukan rekomendasi beli/jual, nasihat keuangan, pajak, atau opini hukum. Data dapat berubah sewaktu-waktu dan wajib diverifikasi ke sumber resmi (BEI/IDX, OJK, BI, kementerian/lembaga terkait, atau laporan emiten). Segala risiko keputusan investasi atau hukum ditanggung sendiri. Lakukan riset mandiri atau konsultasi profesional berizin sebelum bertindak.
Sumber: Kompas.com — Saldo Tabungan Emas BRI Group Capai 20 Ton hingga September 2026. Artikel ini diolah ulang untuk keperluan edukasi/informasi; fakta inti wajib diverifikasi ke sumber asli.
Ditulis oleh Rizki Pratama, CFP® — praktisi investasi sejak 2019, fokus pada emas, obligasi, dan reksa dana.